Forecast 2017 Construction Spending
1-7-17
This is my initial forecast for 2017. Census final revisions to Oct., Nov. and Dec. 2016 spending will not be posted until February, March and April. I will then update the 2017 forecast to reflect better input. Then, with the June 1, 2017 release of spending, Census will post revisions to all 2016 spending. The 2016 record will then be updated.
2-1-17 Updated to include Dec 2016 data
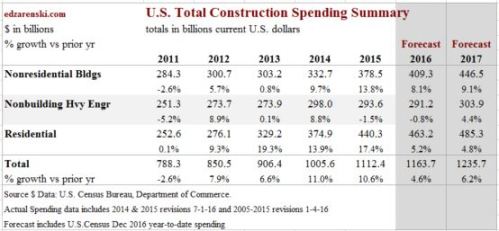
Total construction spending in 2017 will reach $1,236 billion supported by a 4th consecutive year of strong growth in nonresidential buildings. The monthly rate of spending will range from near $1.2 trillion in January to $1.3 trillion at year-end.

Nonresidential Buildings spending in 2017 will increase to $447 billion, 9.1% over 2016. The most recent 3-month average seasonally adjusted annual rate (SAAR) is $420 billion, only 5.5% below the peak of $444 billion in 2008. By midyear 2017 the SAAR will reach a new all-time high and it will finish the year near a SAAR of $460 billion. Office spending will lead 2017 with 30%+ growth. Commercial, Lodging and Educational markets are all expected to post strong gains over 10%.
For details on Nonresidential Buildings, See Behind The Headlines – Nonres Bldgs Construction Spending and Nonresidential Bldgs 2017 Forecasts Comparisons
Non-building Infrastructure, following two down years, will increase by 4.4% to $304 billion, due to growth in the highway and transportation markets. In the most recent quarter spending began to recover from 2016 lows posted in August and September. 2017 will be a record year for Infrastructure spending supported by spending generated from the Fixing America’s Surface Transportation Act and potentially the Water Resources Development Act.
For Non-building Infrastructure details see Infrastructure Outlook 2017
Residential will increase only moderately to $485 billion, adding 4.8% over 2016. That follows on three years of substantial growth averaging 17%/year. More than any other sector residential work is more dependent on new starts within the current year to generate spending, approximately two thirds of all spending within the year.

Office building new starts through August were up only 6% year-to-date but starts in September reached the highest in years. The 2016 starts finished at +37% providing the highest amount of work in backlog going back at least 8 years. Lodging starts in 2016 finished up nearly 40%, Healthcare up 20% and Amusement/Recreation up 35%.
Power project starts dropped 30% in 2016 but from the highest amount of starts on record in 2015. In addition, power had very strong starts in late 2014. All of those very strong starts in late 2014 and all of 2015 are still ongoing in backlog and will contribute to positive spending in 2017. Almost half of all the spending in 2017 is generated from projects that started in 2014 and 2015.

See Also 2016 Construction Spending 1-3-17
Are We at New Peak Construction Spending?
1-4-17
Total construction spending peaked in Q1 2006 at an annual rate of $1,222 billion. For the most recent three months it has averaged $1,172 billion. It is currently at a 10 1/2 year high at just 4% below peak spending. But that ignores inflation.
In constant inflation adjusted dollars spending is still 18% below the Q1 2006 peak.
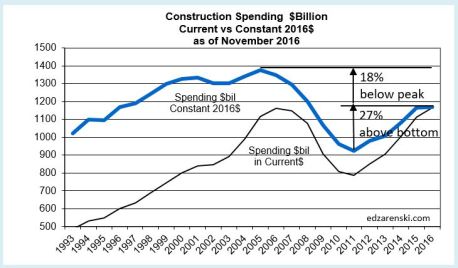
Current headlines express exuberance that we are now at a 10 1/2 year high in construction spending but fail to address the fact that is comparing dollars that are not adjusted for inflation.
In the 1st quarter of 2006 total spending peaked at a annual rate of $1.2 billion and for the year 2006 spending totaled $1,167 billion. We are within a stone’s throw of reaching that monthly level and 2016 will reach a new all-time high total spending by a slim fraction. But all of that is measured in current dollars, dollars at the value of worth within that year, ignoring inflation.
Adjusting for inflation gives us a much different value. Inflation adjusted dollars are referred to as constant dollars or dollars all compared or measured in value in terms of the year to which we choose to compare. To be fair, we must now compare all backdated years of construction to constant dollars in 2016. What would those previous years be worth if they were valued in 2016 dollars?
By mid-2017 total construction spending will reach a new all-time high, but in constant inflation adjusted dollars will still be 17% below 2006 peak. We will not reach a new inflation adjusted high before 2020.
Residential construction spending is still 32% below the 2006 peak of $690 billion. In constant inflation adjusted dollars it is 39% below 2006 peak.
Nonresidential Buildings construction spending is only 3.5% below 2008 peak of $443 billion. However, in constant inflation adjusted dollars it is 18% below 2008 peak.
Non-building Infrastructure construction spending pre-recession peaked in 2008 at at an annual rate of $290 billion. However, post recession it peaked in Q1 2014 at $314 billion. It is now 8% below the 2014 peak. In constant inflation adjusted dollars it is 12% below the 2014 peak.
For more on inflation SEE Construction Cost Inflation – Midyear Report 2016
Nonresidential Bldgs Construction Spending 2017
1-4-17
This is a first pass at 2017 spending. It will be update in February when December starts and spending become available.
2-1-17 updated to include December data
Nonresidential Buildings spending for 2016 totaled $409 billion, UP 8.1% from 2015. Spending posted increases of 9.7% in 2014 and 13.8% in 2015.
Nonresidential Buildings spending in 2017 will increase to $447 billion, 9.1% over 2016. The most recent 3-month average seasonally adjusted annual rate (SAAR) is $420 billion, only 5.5% below the peak in 2008. By midyear 2017 the SAAR will reach a new all-time high. Office, Commercial, Lodging and Educational markets are all expected to post strong results over 10% growth in 2017.

Office building new starts through August were up only 6% year-to-date but starts in September as tracked by Dodge Data & Analytics reached the highest in years. 2016 starts finished at +37% providing the highest amount of work in backlog going back at least 8 years. Lodging starts in 2016 finished up nearly 40%, Healthcare up 20% and Amusement/Recreation up 35%.
Manufacturing – spending will finish down this year, $75 billion vs $78 billion in 2015, but both years are more than 30% higher than the next closest years, 2014 and 2009. Rather than labeling 2016 a down year, 2015-2016 should be described as an extended period of extremely strong spending. 2017 spending will drop the most since pre-recession to $65 billion but will still remain well above 2014. In 2005-2006, manufacturing was less than 10% of total spending in the nonresidential buildings sector. In 2015 it reached 21%. Today it is 18%. Manufacturing in some reports is referred to as Industrial.
Office – spending dropped more than 40% from $65 billion/year in 2007-2008 to $37 billion from 2010 to 2013. Since then it has increased every year by an average of more than 20%/year and is expected to continue that level of growth in 2017. New starts for office projects increased more than 30% in 2016. Office construction 2017 starting backlog (projects under contract as of Jan 1, 2017) is the highest in at least 8 years, more than double at the start of 2014 when the current growth cycle of office construction spending began. More importantly, the ratio of spending from starting backlog is also increasing for 2017. This is setting up a very strong spending growth pattern for the next 2 years. Office construction reached a new all-time high in September 2016. Spending will be in the range of +20% to +30% year over year growth for 2017 with total coming in at $91 billion. Office was more than 16% of total sector spending in 2006 through 2008 before dropping to 13% in the recession. Now at over 17%, it has been growing steadily for the last few years. In 2017 it will be 19% of total sector spending. Offices includes data centers.
Commercial/Retail – this market dropped from $90 billion in 2007 to $40 billion in 2010. It has been growing steadily since reaching bottom in early 2011, but has only recovered to an annual total rate of $78 billion. New starts in 2016 increased moderately. For 2017 spending remains in a tight range between $82 and $84 billion, with total 2017 growth coming in at just over +12%.
Lodging – this market recorded the largest drop of any, falling 75% from $36 billion in 2008 to $9 billion in 2011. However it recorded the strongest rebound of any market climbing 19% to 30% per year for the last 5 years. New starts in 2016 increased almost 40% setting up increased spending from starting backlog in 2017. In 2017, lodging will grow by 12% with a spending total of just over $30 billion. Lodging is still 2 years away from reaching previous highs. Lodging dropped to only 3% of total sector spending in 2011 but has rebounded to 7% in 2016.
Educational – previous highs of over $100 billion in both 2007 and 2008 are perhaps two years away. However, the rate of growth has been increasing slowly since 2014 from 1% to 4.8% to 6.5% annually. New starts have increased every year since 2012. Expect 2017 educational spending to increase by more than 10% to $98 billion. At peak, educational represented 30% of all nonresidential buildings spending. Now it’s only 22%.
Healthcare – this market has been very slow to recover, experiencing declines as recently as 2013 and 2014, hitting an 8 year low in 2014, when all other nonresidential building markets had already returned to growth. 2015 was a moderate growth year, up 5%, but 2016 increased less than 2%. Starts are indicating 5.6% growth to $44 billion for Healthcare spending in 2017. Healthcare has dropped from 14% to only 10% of all nonresidential buildings spending.
Amusement/Recreation – this market hit an 8 year low in 2013 but we’ve had 3 years of excellent growth of 10%/yr or more. 2017 is expected to increase 7.4% over 2016 to a total of $23 billion. This market is only 5%of nonresidential buildings spending.
Religious and Public Safety represent less than 3% of total nonresidential building spending. The religious bldg market has been declining since 2002 and is down 55%. Public Safety peaked in 2009 and has declined every year since, now down 40%.

2016 Construction Spending 1-3-17
1-3-17
U. S. Census posted November construction spending 0.9% higher than October and 4.1% higher than November 2015. Year-to-date spending through November is 4.4% higher than 2015.
With only one month to go, 2016 is predicted to finish at $1,166 billion, up 4.8% from 2015. December spending is projected to come in at an annual rate near $1,200 billion. At this point, in order for total 2016 spending to drop below $1,160 billion, December would need to fall 6% below November, a magnitude of change that simply does not occur from month to month.
Current monthly spending is at a 10 year high and on a current dollar basis (before adjusting for inflation) is exceeded in all historical spending by only 5 months at the peak spending in early 2006. By the 2nd quarter of 2017 spending will reach all-time highs on a current dollar basis. On a constant dollar basis adjusted for inflation we are still several years below peak spending.
For inflation adjusted spending see “Are We at New Peak Construction Spending”
Revised spending for September is 1.25% higher than original posted on 11-1-16 and for October is -0.1% lower than original posted 12-1-16. However, October data is still pending revision again on 2-1-17 and is expected to increase. In the last 3 years every month has been revised up from the original amount posted. 2016 monthly revisions year-to-date average +1.3%.
The table included here shows the predicted total 2016 spending compared to 1st 2016 estimates and current 2016 estimates provided from my data = CA (Construction Analytics) and from CMD (ConstructConnect) and FMI.

What Are You Reading 2016
Thank you to all my readers for making this construction economics blog worthwhile. Here’s ten of my most visited articles in 2016.
Construction Cost Inflation – Midyear Report 2016
Construction Inflation Indices
Starts Point to Robust 2017 Spending
Construction Spending 2016 – Midyear Nonresidential Markets
Construction Spending 2016 – Midyear Summary
How Much Does A Steel Cost Increase Affect Construction?
Saturday Morning Thinking Out Loud #6
Just a few thoughts on forecasting construction spending
If we look at actual data through September, with ~75% of the actual annual construction spending already in the year-to-date and only 25% of annual spending in the estimate to complete in the 4th quarter, if forecasts for year-end totals are not already within 2.5% of the final, that means the projections for the final quarter are off by more than 10%.
Cash flows from construction starts are the strongest predictor of total spending next month. Projects that already started are in backlog. Backlog is used to develop projections for spending. For next month we already have 96% of all work in backlog. The remaining 4% will be new starts next month. For two months out we have 92% and for three months out we have 88% already in backlog. So, the uncertainty on spending in the near term is pretty low. Even averaged over a quarter rather than being exact every month, it takes a major event to have a big miss on projections for the next quarter.
Although exact monthly values in spending may be difficult to predict, trends for monthly changes in spending are easier to predict. Often these trends have very small changes month to month. Monthly changes in spending of +/- 5% are uncommon and changes of +/- 10% are quite rare.
Some forecasts I’ve seen for construction spending would demand that month to month changes in the final quarter exceed 20% to 30%. It’s just not going to happen folks.
Saturday Morning Thinking Outloud #5 – Jobs Growth
For all of 2014-2015-2016
- Total Construction jobs increased from 5,950,000 to 6,700,000, +12.6%
- Total Construction spending increased from $960bil to $1,170bil, +22%
BUT, much of that spending increase is inflation. We need to compare to constant dollars which = Volume. Inflation was particularly high in residential work, over 15% for the 3 years, which means $1.00bil in spending 3 years ago would be worth more than $1.15bil today. Converting everything to constant Oct 2016 dollars, after inflation we get:
- Total Construction volume increased from $1,070bil to $1,170bil, +9.4%
So, for the 3 years, jobs increased by 12.6% while real work volume increased by 9.4%.
A more thorough analysis, which takes hours worked into consideration, shows from the Jan 2011 bottom of the recession in construction to current, both jobs and volume have increased equally by 28%. But jobs growth is often out-of-balance with real volume growth. In the beginning of the recession years of 2008-2011 firms let go of people much faster than work volume declined. 2009 showed a big gain in productivity. By 2010-2011 firms hadn’t let go enough to match the loss in spending. Then from 2012-2014 workload grew faster than firms filled jobs. Since 2011 we are sort of on an even keel.
For the last 3 years, jobs increased more than real construction volume. I pointed this out in my last detailed jobs report. The 6 months from Oct 2015 – March 2016 encompassed the fastest new construction jobs growth period in a decade. It’s no surprise to me that jobs growth has been slow since March this year. Frankly, I wouldn’t be the least bit surprised if it remains slow for awhile. When we look at jobs growth vs. volume growth, there is reason to believe that slow jobs growth is not entirely due to labor shortages. Part of the blame is due to recent over-hiring.
Behind The Headlines – Construction Data
12-2-16
Just a few important facts here (that you won’t read in the headlines).
- Jobs have increased by 23% since the recession bottom January 2011. Construction spending has increased 52% in same period.
- Adjusting jobs for hours worked and spending for inflation, both work output and constant volume construction grew at 28% since recession bottom.
- Residential construction jobs are down 22% from the 2006 peak. In constant $ after inflation, real residential volume of work is down 39%.
- Nonresidential buildings construction jobs are down 8% from the 2008 peak. In constant $ after inflation, real nonres bldgs volume of work is down 17%.
- Construction spending average for the last 3 months is at a 10 year high. Construction volume in constant $ after inflation is still 18% below 10 years ago.
- Census construction data is ALWAYS revised in the following two months after initial release. Census updates all the values for the previous year, usually with the May data release (on July 1) the following year.
- In 2016, 7 times the first release of spending showed a decline vs the previous month. After revisions, the values show no declines vs the previous month.
- In the last 36 months, there were 16 spending releases that originally showed a decline vs the previous month. After revisions there were no mo/mo declines.
- It’s hard to add $100 billion in new construction spending in one year. Since 1993 it’s happened only 3 times; 2004, 2005 and 2015.
- It’s real damn hard to add $100 billion in new construction volume in a year. After adjusting for inflation, construction volume has never increased by $100 billion. It has increased by $75 billion 4 times and 3 more times by $50 billion.
- It takes about 6,000 jobs to put-in-place $1 billion of construction in a year. $100 billion in new work would require 600,000 new jobs in a year. The largest construction jobs growth ever recorded is about 700,000 jobs in 2 years.
- Now think of #9, #10 and #11 in terms of ONLY the Infrastructure sector. Infrastructure, about 25% of total construction spending, added spending more than $25 billion in a single year only once. The average annual growth for the past 20 years is less than $10 billion/year. The average growth in jobs (excluding all recessionary years because they would make the result approach zero) is about 25,000/year.
- The Aug-Sep-Oct 3mo average of construction starts for Nonresidential Bldgs (by Dodge Data) is the best 3mo since Q1 2008. Q1 2008 was the PEAK of the nonresidential buildings construction boom.
- More infrastucture projects started construction in the 1st 6mo of 2015 than any time in history. This will boost infrastructure spending through 2017. Infrastructure spending is low in 2016 due to a low volume of starts in 2014.
Construction Spending Oct 2016
12-1-16
October construction spending put-in-place was released today by U.S. Census. This report includes the first revision to September data and the 2nd revision to August.
LINK TO U. S. Census October Construction Spending Release 12-1-16
October spending 1st release came in at $1.172 billion, 0.5% higher than September which was revised up 1.4% to $1.166 billion from the 1st release of $1.150. August was revised up 2.1% to $1.166 billion from the 1st release of $1.142.
I predicted October spending would come in at $1.190 billion. Once revisions to October data are posted in Nov and Dec, we may reach that $1.190 billion forecast. Revisions have averaged over 1.4%/mo this year and 1.5%/mo for the last 4 months.
Average spending for the last 3 months is $1.169 billion, the highest three-month average since May-Jun-Jul 2006.
Year-to-date (YTD) spending is up 4.5% over last year, but this may go even higher once the revisions are in. There is now no doubt that we’ve clearly passed a previously forecast dip in spending that bottomed in Apr-May at $1.142 billion. The last 5 months of spending are all up from the low point and the trend is pointing higher.
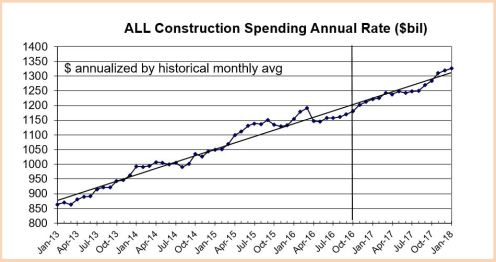
My forecast for total spending in 2016 is $1,168 billion, up 5% from 2015. I expect 7.6% growth in 2017.

MAJOR SECTORS
Residential spending is up 5.5% ytd and is on track to reach a 2016 total of $468 billion, +6.4% over 2015. Last year, peak spending was in September, then residential spending dropped slightly in Q4 2015. This year I expect 2016 spending to peak in Q4, so we should see ytd performance get better as we approach year end. Cash flow from new starts indicates growth of 9% in 2017 spending.
Total Nonresidential spending is up 3.8% ytd, on track to finish 2016 with total spending at $700 bil, up 4.2% over 2015. Almost all the 2016 growth is in nonresidential buildings, not infrastructure. For the 4mo period Jul-Oct 2016, compared to the same 4mo in 2015, all nonresidential spending is up only 1.7%, but the spending trends are not apparent unless we separate nonresidential buildings from non-building infrastructure. For Jul-Oct 2016, compared to the same period a year ago, nonresidential buildings spending is up 7.6% and non-building infrastructure is down 5.4%.
Nonresidential Buildings spending is up 8.2% ytd through October, led by Office, Lodging and Commercial Retail markets. We should finish 2016 up 8.1% with a total at $409 billion vs. $379 billion in 2015. Total sector growth for the last three years is 35%. I’m predicting 2017 spending for Nonresidential Buildings will increase 7.5%, led by Educational and Office spending.
We are currently at what may be 2016 peak nonresidential buildings spending. I’m expecting nonresidential buildings spending to stall or drop 1.5% to 2% over the next few months before resuming growth. This drop may be in large part due to uneven starts from the end of 2014 and beginning of 2015, a period when starts were abnormally high, that are now finishing and dropping out of the monthly spending values. Usual normal growth patterns in starts do not fill the void left when abnormally high volume of projects finish.
Non-building Infrastructure spending is down 1.2% ytd. Infrastructure spending in 2016 will total $291 billion, down less than 1% from 2015. Spending predicted from Dodge Data Starts predicted this drop. Negative drivers are Transportation, contributing -0.9% to overall decline, Sewage/Waste Disposal -1.0% and Water Supply -0.4%. Power, the largest infrastructure market at 33% of total, is up 1.4% ytd so adds about +0.5% to offset some of the declines. Highway/Street, 31% of infrastructure, is up only slightly. Growth resumes in Q1 2017. Although new starts in 2016 will finish down 10%, starts in 2015 were so high that 2016 will still be a good volume of new starts. Predicted spending from starts is indicating 2017 will be a record year for spending on infrastructure, up 7% from 2016.

PUBLIC MARKETS
Public spending is down 1.5% ytd, on track to finish 2016 with total spending at $285 billion, down 1.4% from 2015. Public spending will rebound in 2017, up 6.5%.
Educational spending is 80% public and 20% private. Education accounts for 25% of public work. Educational is by far the largest building type in public work. All the remaining building types contribute only 2% to 4% each.
60% of all public work is infrastructure. Highway/Street accounts for 31% of all public work. Transportation facilities is 11% of public work, Sewage and Waste Water 9% and Water 4.5%.
The biggest drivers of performance in public markets by far are Highway/Street and Educational spending. Highway/Street spending reached all-time highs from Dec 2015 to March 2016 but is currently 10% below that level and will end 2016 down 1% from 2015. In public markets educational is only up 5% ytd, but in October experienced the largest monthly increase in the public sector.
REVISIONS AND YEAR/YEAR COMPARISONS
Census construction data is always revised in the following two months after initial release. Census revises data and incorporates more data from additional sources to update spending values. Census updates all the values for the previous year, usually with the May data release (on July 1) the following year.
For the 1st nine months of 2016, seven of nine times the first release of spending showed a decline vs the previous month. After revisions, the values show no declines vs the previous month. The last 36 months of data shows there were 16 Census releases that originally showed a decline vs the previous month. After revisions there were no mo/mo declines in the last 36 months. Revisions in 2016 have averaged 1.4%/mo and 1.5%/mo for the last 4 months.
In 2015, spending peaked in the months of July, August and September, then dropped slightly and remained flat for the last quarter of the year. This 2015 pattern, along with the issue of revisions noted above, is one of the reasons comparisons of 2016 to same month last year was low for August and September. A growth trend is now in place. Expect this month vs same month last year for the remainder of 2016 to come in near or above +5%.
RELATED POST
10-20-16 Starts Point to Robust 2017 Spending
Saturday Morning Thinking Outloud #4 -YTD
11/26/16
In 2015, nonresidential buildings starts were very high in the beginning of the year and dropped off in the later part of the year. In 2016 it’s just the opposite. This skews year-to-date total comparisons and for most of this year makes it appear as if there may be no growth in new starts.
Here’s a simple example:
Let’s say 4 months in 2016 had starts of $6, 8, 10 and 12 billion and the same months in 2015 had starts of $10, 9, 8 and 7 billion. The year-to-date change for 2016 vs 2015 after the 1st month (6 vs 10) is down 40%. After two months it’s 14 vs 19 (6+8 vs 10+9), down 26%. In the 3rd month 2016 has better performance than 2015 (10 vs 8), but the year-to-date (24 vs 27), down 11%, is still strongly influenced by the earlier months. But in the 4th month we get 36 vs 34 and finally the year-to-date shows 2016 growth of 6% over 2015. That is the current scenario.
Construction Starts for nonresidential buildings for the 1st 4 months in the 2nd half of 2016 (Jul-Oct) are 30% higher than the average of the 1st half 2016 and almost 40% higher than the same 4 months in 2015, and yet the year-to-date % change 2016 vs 2015 is ZERO.
To keep from being misdirected, year-to-date comparisons require knowing not only the direction of the current year trend but also the direction of the previous year trend.
The most recent 3 month (Aug-Sep-Oct) average of nonresidential buildings construction starts by Dodge Data represent the best 3 months since Q1 2008. Although year-to-date performance of zero growth would seem to indicate a slow down, starts are doing just fine. I’m forecasting the final two months of the year to be up 40% from 2015.
But wait, there’s more!
Every year, starts from the previous year are adjusted, always higher. 2016 starts won’t be adjusted up until 2017. But that means all current 2016 (un-adjusted) starts are being compared to 2015 that has already been adjusted up. This causes the year-to-date comparison to be always understated. The average adjustment to nonresidential building starts for the last few years has been about +5%. If that trend remains consistent then next year we should see that 2016 starts were approximately 5% higher than first posted and growth was really much better than current values would seem to indicate.
With 10 months of data in hand, year-to-date starts for nonresidential buildings show no change from 2015. However starts are doing very well and I’m predicting the 2016 volume of starts will lead to 8% growth in spending in 2017.